Taxing False Premise, Second Round

In a recent Wall Street Journal op-ed, Senator Ron Wyden (D, OR), Senate Finance Committee Chairman, labored under the same false premise as the international collaboration effort.

While decrying the loss of US companies as they move overseas to avoid the US’ highest in the world corporate tax rate, he insisted

America’s tax base erodes at a cost of hundreds of millions of dollars in revenue, increasing the burden on other companies and individuals. America also loses good jobs, talent, investment, and the ability to compete on a global stage.

Legal or not, this loophole must be plugged.

Once again: it isn’t possible for government to incur a “cost of hundreds of millions of dollars in revenue” when it isn’t government’s…revenue…in the first place. Certainly, government sees a reduction of “millions of dollars” from these moves, if we elide—as Wyden does—the dynamic effects of real tax reform.

However, the right answer isn’t Wyden’s, who demanded

Current law requires that US companies reincorporating overseas must ensure that at least 20% of their stock is owned by their new, foreign partner. As chairman of the Senate Finance Committee, I am committed to raising this floor to at least 50% for all inversions taking place from May 8, 2014, on.

This move is—how shall I put this delicately—brain-dead. Just as companies have found and are finding legal ways around existing tax law, and by the way, leaving profits earned overseas overseas due to our usurious corporate tax rates, they’ll find ways around Wyden’s 50% threshold, too. All Wyden will get out of this is feel-good and frustration, if he’s sincere in his effort, and open-ended political gain from his base if he’s not.

Wyden will not get anything material done regarding his concern for “increasing the burden on other companies and individuals.” Nor will he accomplish anything meaningful for his loss of “good jobs, talent, investment, and the ability to compete on a global stage.”

No, what’s needed is what is the first step in any recovery program: recognize and acknowledge that he has a problem. His notion that taxes are government’s money has to go, to be replaced by recognition that it’s our money, granted to government only for purposes that suit us, not that suit government.

The next step is to lower US corporate tax rates (eliminate corporate taxes altogether, say I, but a sharp reduction is a good early step), and then to make it easier (not harder) to partner with overseas companies (including in those companies’ taxing jurisdictions) and cheaper (free would be good) to repatriate profits earned overseas to the US.

Wyden thought he was addressing tax rates, too, in his op-ed.

A [lower] corporate tax rate that creates a favorable investment climate and reduces the incentive to game the system is critical to successful reform. … Where the rate ends up depends almost entirely on the American business community’s willingness to pitch in by closing loopholes.

There’s that false assumption that it’s the government’s money, again. This time it leads to the false conclusion that tax reform must, somehow, be revenue neutral. That may be useful politically, but it’s useless to true tax reform. There’s no need to “close loopholes” in return for lower tax rates. Loopholes need to be closed, certainly, but in order to reduce government social engineering through our tax code, not in order to preserve revenue that isn’t government’s to begin with. Of course, eliminating corporate taxes altogether would close all those loopholes….

Wyden wants global competition? Let other nations compete with us, beginning with lowering their business tax rates in their resulting newfound need to keep their companies from relocating to the US. With foreign talent coming here, while ours stays here. For good jobs in the US, for investment in the US.

Oh, and the lower tax rates also will decrease “the burden on other companies and individuals.”

There’s competition. It can come only from correcting that premise, though.
Taxing False Premise

The US is about to join an international tax collaboration scheme involving the People’s Republic of China, Australia, Japan, and Great Britain that’s designed to improve tax collections from multinational corporations. It’s also designed to increase government reach into private enterprises and government control over them.

Leave those last two design purposes aside, though.

Australia’s Commissioner of Taxation, Chris Jordan, said this about the scheme:

This collaboration has allowed us to better understand what is happening in our own countries and determine whether what is being represented in one country reflects what is being represented in another.

Fair enough. Nations of laws, as most of these participating nations are, should be able to enforce their tax laws, also, and the taxees ought not be telling conflicting stories to differing jurisdictions.

The Wall Street Journal at the above link cited “some estimates” as claiming that “the world’s governments lose US$3 trillion in tax revenue a year” to multinationals’ moves to adjust their own revenue collections to the most favorable tax jurisdictions.

And therein lies the false premise. In free countries—the US, Great Britain, Australia, and Japan in the present context—it’s not the government’s money; it’s the tax payers’ money, and they only allocate some of their money to their respective governments as tax payments. The governments aren’t losing a dime to legal tax payment minimization or avoidance schemes. It isn’t possible for them to lose what isn’t theirs in the first place.

Will We Get a Cut in our Gas Tax?

Now the Obama administration wants to let the states charge tolls for the use of the Interstate highway system. This is the system for which our road and fuel taxes have already paid; the states’ tax money is supposed to be for maintenance and repair of the system.

OK, fair enough. Those roads won’t repair themselves.

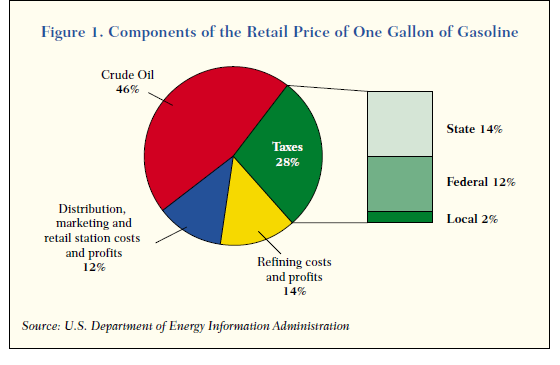
But we still pay those road and fuel taxes, and those funds are for maintenance and repair. This graph from the US Department of Energy, via the Center on Urban and Metropolitan Policy‘s Fueling Transportation Finance: A Primer on the Gas Tax, gives a breakout of what went into the price of a gallon of gas as recently as 2002.ComponentsOfGasPrice

Federal taxes were 12% of the price, or about 44¢ per gallon here in north Texas (updated to 2014).

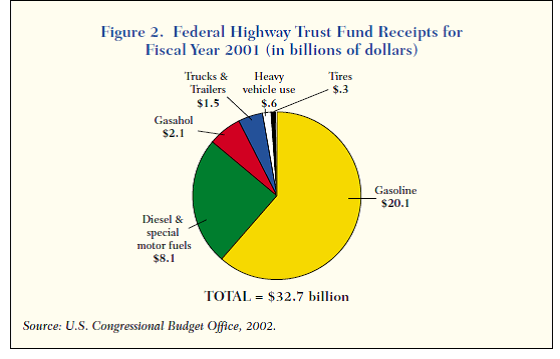
This graph, from the CBO via the same article, gives the 2001 breakout of Federal receipts for the highway trust fund.FederalHighwayTrustFundReceipts

Gasoline and diesel fuels—car and truck fuels—comprise the vast bulk of the receipts.

This 2007 table from the Federal highway administration updates those breakouts.

Table 4. – User Fee Structure.
Tax Type Tax Rate
Gasoline and gasohol 18.4 cents per gallon
Diesel 24.4 cents per gallon
Special Fuels:
General rate 18.4 cents per gallon
Liquefied petroleum gas 18.3 cents per gallon
Liquefied natural gas 24.3 cents per gallon
M85 (from natural gas) 9.25 cents per gallon
Compressed natural gas 18.3 cents per 126.67 cubic feet
Tires: (maximum rated load capacity)
0-3,500 pounds No Tax
Over 3,500 pounds 9.45 cents per each 10 pounds in excess of 3,500
Truck and Trailer Sales 12 percent of retailer’s sales price for tractors and trucks over 33,000 pounds gross vehicle weight (GVW) and trailers over 26,000 pounds GVW
Heavy Vehicle Use Annual tax: Trucks 55,000 pounds and over GVW, $100 plus $22 for each 1,000 pounds (or fraction thereof) in excess of 55,000 pounds (maximum tax of $550)

Notice in the table that taxes are broken out, also, by vehicle weight. Trucks with tire capacity over 3,500 pounds are the trucks that ship our goods over the highways.

Cars and trucks—including those shippers—comprise the vast bulk of the Interstate highway users. Guess who’ll pay the tolls. And who’ll pay higher prices for the goods we buy after they’ve been shipped to the stores we frequent.

Will we see compensatory reduction in our fuel taxes, which as noted above already exist in major part to pay for interstate highway maintenance?

Fat chance.

Yet Another Thought on Social Security

James Pethokoukis, writing for AEIdeas, had one, and I have some thoughts on his thought.

Pethokoukis first:

To counter the anti-growth impact [of Americans’ of increasing lifespan and falling birthrates] you would need (a) greater labor-force participation, (b) higher birthrates, (c) greater innovation so each worker is more productive.

To which I add, (d) higher immigration rates with better assimilation into American society. We need more folks, with their fresh ideas, their initiative, their drive, their (conservative) family values and sense of responsibility, all of which are amply demonstrated by the lengths to which they go to get here.

Second [citing colleague Andrew G Biggs, who was writing in National Affairs], “Social Security’s government-provided benefits would be transformed into a flat universal benefit mean to improve social-insurance protections for low-income Americans.”

The short question is how to handle the erosive effects of inflation. That’s only partially, and hopefully, addressed by Biggs’ view that this would grow over time with wages. But there’s a larger problem, it’s in Biggs’ article, and it’s one that Pethokoukis missed.

The two parts of Biggs’ solution are these. First, enroll all workers in an employer-sponsored 401(k)/403(b) type device, with the employees required to contribute, say 1.5% of their pay and employers required to match that dollar for dollar. Second,

Social Security’s government-provided benefits would be transformed into a flat universal benefit to improve social-insurance protections for low-income Americans. … Each American reaching the normal retirement age would receive a benefit set at the poverty threshold for individuals over age 65….

The larger problem involves both of these, and both are solved by privatizing Social Security and making each person’s payments go into a retirement account for the payer’s future retirement rather than for strangers’ current retirement (they’re not even specifically for the payer’s parents’ current retirement).

We’re used to paying 6.2% of our payroll tax into social security. Pay those 6.2% instead into a retirement plan (401(k)/403(b), Traditional or Roth IRA, etc) whose proceeds are for the sole benefit of the payer, and which accounts are under the sole control of the payer, for his own future retirement. Also, remove the income and contribution caps. So what if the better off can pay in more in than can the less well off? Those larger payments in no way hurt the less well off, and the increased consumption available to those better off is good for the economy—and everyone else. Next, free the employer from the matching payroll tax altogether. The employer will benefit from that reduction in labor cost and can use the money to make the business more competitive—including matching employee retirement contributions as a competitive device—which will be good for hiring.

This makes each worker responsible for his future welfare, and he’ll do a better job of taking care of that than the government can, as demonstrated by Social Security’s current fiscal straits. It also eliminates the need for Biggs’ flat benefit for the less well off. Their own retirement accounts, allowed to accrue for their future benefit instead of being paid out immediately as Social Security does now, and at a faster rate than Biggs’ alternative, does the deed.

“How to Energize a Lackluster Economy”

I’m playing off Edward Lazear’s Wall Street Journal op-ed of the same title.  In his piece, he touted the benefits of a consumption tax over an income tax, but his argument flows from a number of false premises.

Lazear asserted

…over 30% of US gross domestic product is taxed away to fund federal, state, and local governments.  Tax compliance costs are also large, estimated to be around 1% of GDP.

The hidden cost of the tax system is the biggest of all—namely, the slower economic growth that results from taxing investment, which impedes the formation of capital and hinders productivity and wage growth.

So far, so good.  These taxes and their associated compliance costs are way too high (and, using 2007 data, a flat tax of 10%, with no deductions, credits, or what-have-yous that everyone pays would net the government an increase in revenue compared with the current system.  Now, whether the government needs that increase is a separate discussion).

But then he said

An easy way to remove the impediment to growth is to move toward a consumption tax by allowing the full and immediate deductibility of capital investment.

Here begins his first false premise.

The argument rests on two points.  First, consumption taxes are better for economic growth than are income taxes.

No, they’re not.  Consumption taxes are horribly regressive, and they actively hurt the poorest among us the most.

Second, allowing full expensing (immediate deductibility) of investment turns the current tax system into a consumption tax.

His second false premise is an implied one: that (income) tax structure and rates should remain essentially as high as they are, other than his deductibility of capital investment.  See above about lowering rates and eliminating deductions, credits, etc.

He went on:

Consumption taxes [his capital investment taxes] are better for economic growth because they create stronger incentives to save and invest than do income taxes.

Under an income tax, a person who consumes what he earns immediately is taxed once, specifically on the earnings that he receives in that year.  If instead he invests what he earns, the interest on that investment, which is compensation for deferring consumption, is also taxed.

This rationalization of his first false premise, though, is centered on yet a third (again implied rather than explicit) false premise: that our tax system should be used for social engineering at all—here, attempting to push money uses into this purpose instead of that—instead of solely for the three explicitly identified purposes for which taxes are permitted under our Constitution.  Those three permissible purposes are, as any grade school civics student knows, are to pay the nation’s debts, to provide for the nation’s defense, and to provide for the general welfare, which itself is explicitly defined by the next 16 clauses of Article I, Section 8.

There’s a fourth false premise (yet again, implied) that underlies all of Lazear’s argument: that businesses should be taxed at all.  Since business taxes are just another cost center for businesses, their taxes, like their other costs, are passed on to their customers—ultimately us—in the form of higher prices.  In the end, then, we pay the business’ taxes, even though it’s the company CFO who signs the check to the Treasury.

No.  Better instead to change the income tax system altogether to a flat tax (I argue for a 10% rate) that every citizen and no business pays.  No social engineering by taxation.  Full stop.

With that in place, watch how thoroughly our economy is energized.