Market Disruption

…is what happens in a free market, and one result is wealth redistribution, not by inefficient, politically motivated government mandate, but morally and efficiently by voluntary exchange among market participants—folks like you and me. One example of this is the price of taxi medallions.

…leading cabbies and fleet owners throughout the USA worried that their industry will be decimated if local and state government doesn’t intervene.
…
In Chicago, which has the country’s second biggest fleet with roughly 7,000 taxis, the median sale price for a medallion hovered around $70,000 in 2007 before reaching a median sales peak of $357,000 in late 2013.

Since reaching that high point more than a year ago, the value of medallions in the Windy City have sharply declined and sales have ground to a near halt—with the city recording only seven medallion transfers in the first quarter of 2015….

(Aside: can you see the bubble in that?)

Now cabbies and fleet owners are worried about the prices of their medallions and want government to “intervene.”

Cabbies around the country complain that drivers for services like Uber, which use a smartphone app to connect riders with freelancers using their own vehicles, are disrupting the market and playing with an unfair advantage.

Not so much of an unfair advantage. Nothing is stopping the “official” cabbies from using the same sort of smartphone application to achieve the same thing: on demand, low cost rides for the customer. It’s certainly true that the price of a medallion is tanking (but really: 70 large for a license to drive a car for hire? What supports that sort of pricing other than a government protected monopoly?)

Let’s look at the wealth redistribution of a medallion-for-sale monopoly and an Uber or a Lyft, in which anyone can play for as long or as briefly as they wish.

With the medallions—especially with their cost—cab fleets charge high prices per fraction of a mile on the trip, with government-mandated price floors (in addition to the monopoly aspect, a need presumably driven by the necessity of recovering the cost of the license to operate represented by that medallion). Wealth is transferred from the customer to the cab fleet owner, and the customer gets a ride to his destination. When the cabbie can, or is willing to, get to the customer’s location.

With an Uber-like operation, a customer can make his wish known via his smartphone, and a ride-share participant arrives promptly (because there are a lot more of these than there are formally licensed cabbies), and the customer gets his ride, at a rate commensurate with the area and the demand for rides in the area, but at a significantly lower price than the medallioned cabbie. The wealth redistribution is at that lower rate—competition, you know—and the money transferred goes directly to the driver (minus some Uber overhead, which isn’t much compared to that medallion, just for starters).

The fact of that lower price, and the ubiquitousness of what are essentially part-time and wholly voluntary drivers (who are driving as an additional thing, not as their day job) demonstrates that the fleet cab pricing is excessive relative to the industry needs: the alternative to the formal fleets simply have a much lower cost structure.

That’s a thing to be celebrated, however disruptive it may be to the establishment. Medallion cabbies and buggy whips….

Lots of folks are getting a service they want at a lower price than heretofore, and lots of folks are getting some extra money—lots more folks than the special few who drive medallion-permitted cabs.
The Ex-Im Bank

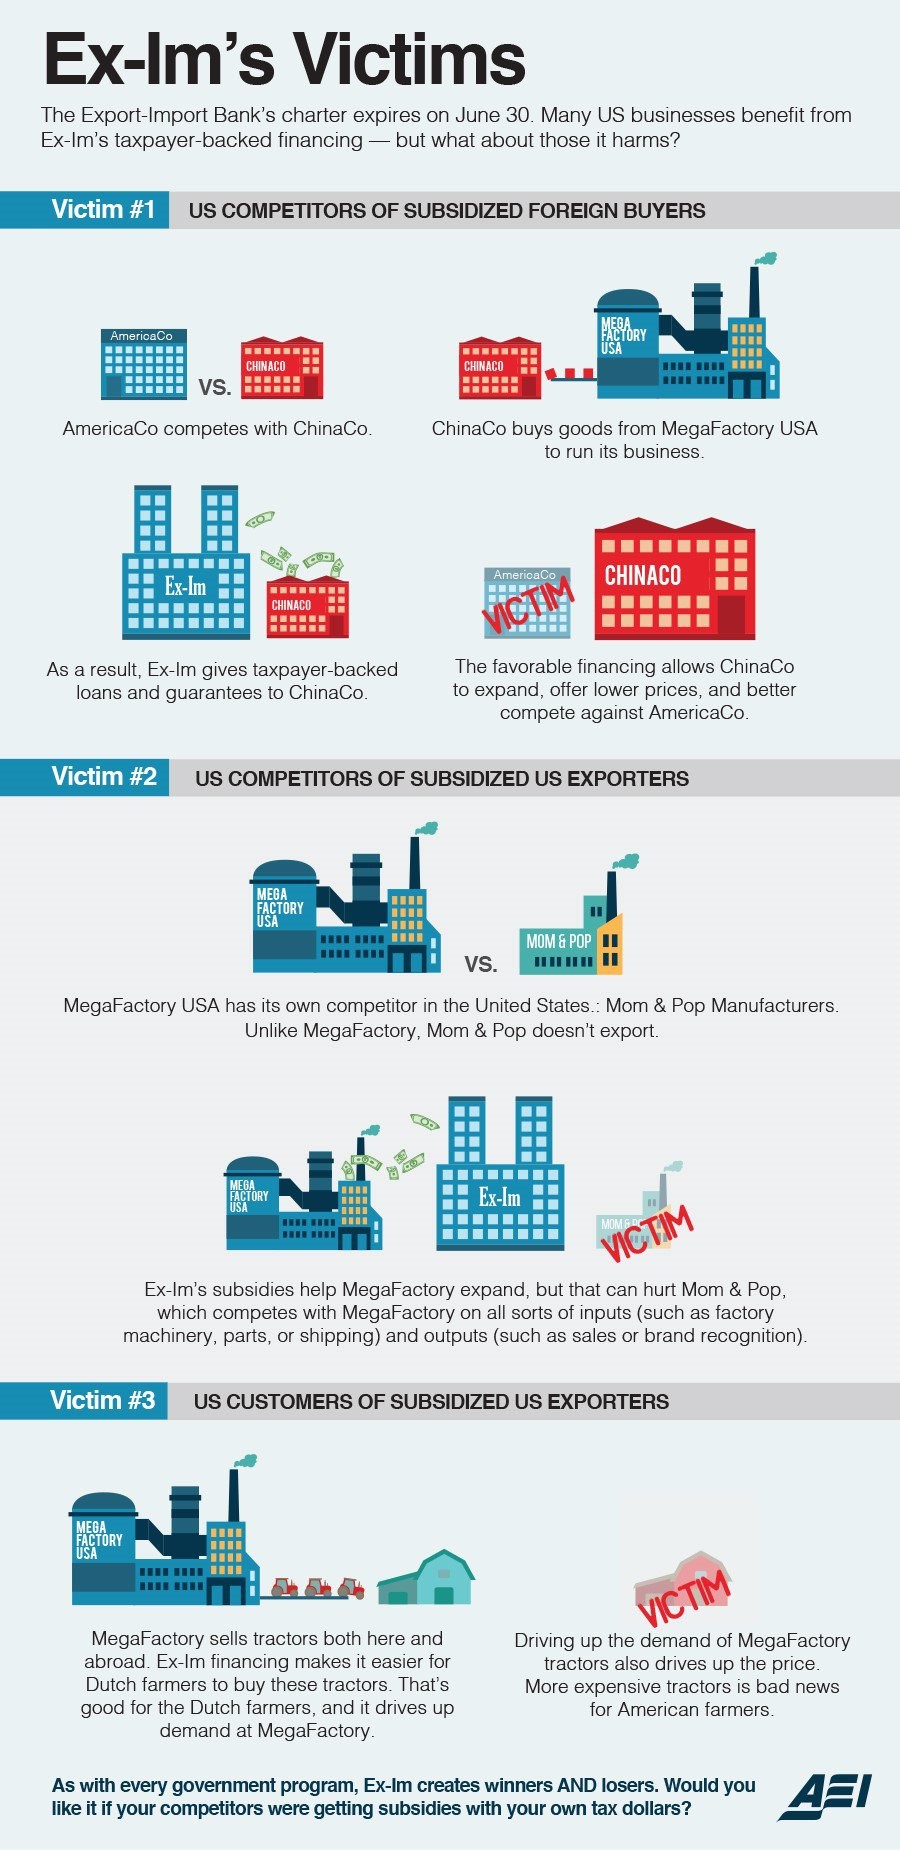
The Export-Import Bank’s charter is up for renewal in our Congress this spring. The bank is alleged to help American companies by lending money to foreign buyers of and American company’s products so that buyer can afford the purchase, which in turns helps the US company, and its employees.

That’s a pretty good deal, right?

Maybe not so much. It’s American taxpayers who are on the hook—not just the one American company and its employees—if the foreign buyer defaults on the loan. But that’s not all. American companies trying to compete with that foreign buyer also are harmed, whether or not that foreign buyer defaults. See the graph below, from AEIdeas:ExImBank

Don’t renew the bank’s charter.

A Thought on the TPP

Japanese Prime Minister Shinzo Abe spoke one out loud while addressing our Congress a bit ago. The Trans-Pacific Partnership agreement is more than just a trade agreement, he said.

What the TPP is all about [is an opportunity to] spread our shared values and have them take root: the rule of law, democracy, and freedom.

What he said.

The SEC’s Abuse of Authority

Actually, it’s Dodd-Frank’s abuse, and the SEC is only implementing the abuser’s requirement, but still….

At issue here is an SEC proposed rule that purports

to give investors greater clarity about the link between what corporate executives are paid each year compared to total shareholder return—the annual change in stock price plus reinvested dividends, according to people familiar with the measure.

There are a couple of things wrong with this. One, minor on the scale of this…rule’s…transgression is the idea that stock price and dividend handling are the measure of a business’ management. No, these are the outcomes; the actual measures are on the business’ financial sheets. Those P&L, Cash Flow, and Balance Sheets, among a host of other performance reporting documents, are freely available to shareholders—and to prospective shareholders: they’re public documents.

The larger problem, though, is this: the executives’ performance is the business of the shareholders, not the government. This is just a backdoor effort to insinuate government deeper into the management of private businesses.

Dodd-Frank needs to be repealed, and D-F-related SEC (and others’) rules rescinded as soon as this administration can be replaced.

Venture Capital

The Department of Energy’s Loan Guarantee Program—its green energy loan program—is a money loser, according to the GAO.

The Government Accountability Office says the DOE’s oft-touted $28 billion loan program will cost taxpayers $2.21 billion over the lifetime of the loans. Not only that, the costs to taxpayers for green loans has risen about $500 million as “the result of loan guarantee defaults” from companies like Solyndra and Abound Solar.

That’s not bad by itself; the sorts of projects and companies being loaned to via this, essentially, venture funding program are high risk, losses are normal, and for a venture capital effort to lose money overall isn’t at all unusual.

What makes this particular program and its losses bad, however, is that it’s a government program. True venture capital entities, whether they fund through lending or any other method, are private companies. The participants in a private venture capital enterprise are voluntary participants who know, or have the opportunity to learn, beforehand the risks entailed in such a thing and who commit their own money to the effort.

When government gets involved in venture capitalism, the participants—the taxpayers—are not voluntary, they’re dragooned into the effort by the government’s commitment of those taxpayers’ money; the taxpayers have no opportunity to evaluate, before their money is irrevocably committed, the risks being run; and government is committing OPM to the enterprise, not its own money (indeed, the government has no money of its own to commit; it has only those taxpayers’ money).

Government has no legitimate role in the venture capital market.