
Two Economic Plans

Here is a sort-of side-by-side comparison of Senator Rick Santorum’s economic plan with Governor Mitt Romney’s plan—only sort-of because they address different things in addition to their areas of overlap.

Senator Santorum opened the discussion of his plan with this:

…Obamanomics has left one in six Americans in poverty, and one in four children on food stamps. Millions seek jobs and others have given up.

while Governor Romney had similar words to introduce his plan:

We have record-breaking unemployment and deficit spending, and a tax code that looks like it was devised by our worst enemy to tie us in knots. These three afflictions are interconnected. I have a plan to address them and achieve three goals: more jobs, less debt, and smaller government.

Economic Area

Santorum’s Plan

Comments

Romney’s Plan

Comments

Individual Taxes

only two income tax rates of 10% and 28%. triple the personal deduction for children, eliminate the marriage tax penalty. Strong step in the right direction in simplifying through reducing the number of tax brackets while reducing tax rates.But why keep the distorting subsidy? 20% reduction in marginal individual income tax rates A step in the right direction, but it maintains the multiplicity of tax brackets


reduces tax rates for businesses that pay at individual rates and employ the majority of private-sector American workers Through the above 20% reduction


abolish the death tax.  repeal the Alternative Minimum Tax Unequivocally good moves


place some curbs on personal tax deductions, exemptions and credits Such as…?

Corporate Taxes

corporate tax rate halved to a flat rate of 17.5%. expense all business equipment and investment. Taxes on corporate earnings repatriated from overseas eliminated Again a sound move.  But see my summary below about manufacturing taxes. reduce the corporate tax rate to 25% from 35%, transition from a world-wide taxation system to a territorial one A good step in the right direction.Especially, the territorial tax system can be very beneficial, depending on its details.


make the R&D tax credit permanent Lower the tax rate further, and this distortion isn’t necessary.  Nor will it be necessary y to weasel-word what constitutes R&D.


maintain the 15% rate on capital gains, interest and qualified dividends, and eliminate the tax entirely for those with annual income below $200,000. Mostly maintains the status quo, but the differential treatment of groups of Americans just continues Obama’s class warfare.Also, see above concerning distortions and tax rates.


broaden the corporate tax base. In what way, exactly?

Federal Spending

spending cuts of $5 trillion over five years, including cuts for the remainder of fiscal year 2013 A sound start, but reduced spending in what areas?


cut means-tested entitlement programs by 10% across the board, freeze them for four years, and block grant them to states A good start, but why not reduce the size of the grants each year until they’re eliminated?  These are supposed to be State programs: get the Federal government out of them altogether.

Federal Budget

propose budgets that spend less money each year than prior years Reduced spending in what areas?


submit to Congress a budget that will balance within four years; call on Congress to pass a balanced-budget Constitutional amendment which limits federal spending to 18% of GDP. Reduced spending in what areas?An Amendment can be good or bad depending on how it’s written.Finally, calling for a thing is easy to do….


Unstated in his present plan is his prior insistence on continuing to use our tax code to perpetuate the myth of the usefulness of government-centric economic engineering: he singles out manufacturing for especially low tax rates—no manufacturing corporate tax at all.

In addition, Santorum had this to say about jobs: he’d approve the Keystone XL pipeline, and he’d repeal all “Obama administration regulations that have an economic burden over $100 million.”  I don’t understand, though, why he exempts similar regulations from earlier administrations.  He also insists that Federal agencies must use “sound science and cost benefit analysis;” although here, too, he’s short on specifics, like what analyses fit this bill, or what constitutes “sound” science and cost benefit analysis.

Santorum also says he’ll work to replace Obamacare with “competitive insurance choices,” but without saying what constitutes “competitive” in his view—and he claims to be able to achieve this while maintaining a mandate that somebody must “protect those with uninsurable health conditions.”

Finally, he promises to present to Congress five free trade agreements his first year—but with whom?

Romney, on the other hand, expects his lower taxes to stimulate job growth.  He’s not far wrong here, but more specifics about jobs would have been nice in addition to those tax system generalities.

Both plans are vague on spending cuts, and both continue market distorting subsidies/tax credits of one sort or another—never minding that these simply continue government-generated distortions in our economy, driving up the prices of things that are subsidized and forcing all of us to pay for those price increases, whether we buy the subsidized item or not.  The two plans also emphasize different sides of the revenue coin: Romney focuses on the tax system while Santorum dwells more on spending and budgeting.

In the end, both plans, shortfalls and all, are enormous improvements over the Progressives’ plan of increased spending, higher taxes, exploding debt, and starker class warfare.
Debt, Spending, and Taxes Revisited

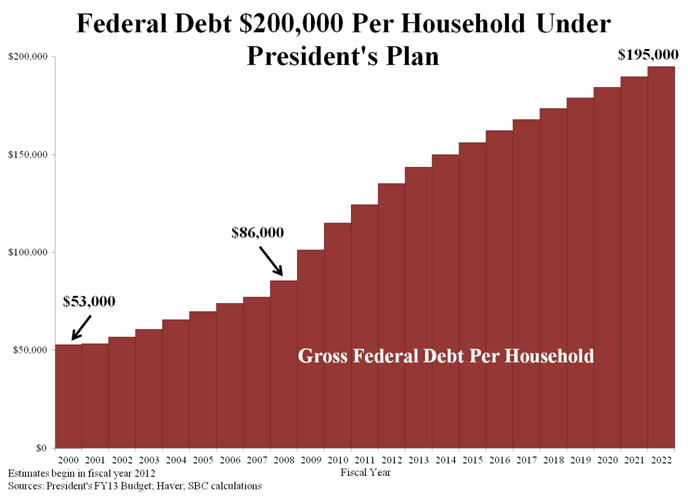
PowerLine has a couple of graphs that tell the story in President Obama’s own words.  Of course, he wants to raise corporate taxes in part to cover this shortfall, even though raising taxes, beyond a level long since surpassed, reduces tax revenue collected as businesses (and individuals, in response to parallel attempts to raise taxes on them) do what comes naturally for all of us: look for ways to hang onto what’s ours, rather than give it up to a ravenous government.

The graphs are clear in their own right; I’ll say no more here.

Remember this in November.

Another 2nd Amendment Question

But it’s (ostensibly) for a good cause: Illinois State Representative Kelly Cassidy (D, Chicago) wants to tax the sale of ammunition and use the proceeds to help defray the costs of “high-crime area” trauma centers that treat the results of violent crime.

Illinois Campaign to Prevent Gun Violence Campaign Director, Mark Walsh, actually argues with a straight face

[The money would go] into communities here in Illinois that have been damaged with gun violence.  I think it’s a legitimate way to pursue funding.

This is, at best, naïve.

Illinois State Rifle Association Director, Richard Pearson, makes things clear:

[Criminals are] not buying their ammunition (legally). They’re not paying any part of the tax. They’re getting their stuff illegally[.]

Taxing the law-abiding to pay for the criminals’ actions doesn’t address the problem—that violent crime.  If Illinois wants to lower the costs of violent crime outcomes, the answer is straightforward: reduce the incidence of violent crime.  This begins with enforcing crime laws, even in those “high-crime areas,” not waiting until the violence has been done, and then looking for ways to cover the price.

It’s unacceptable to expect law-abiding citizens to subsidize the outcomes of enforcement failure.  State Congresswoman Cassidy knows this full well—her move is nothing more than another attempt to restrict our firearm possession and ownership and use rights.

Obama’s Tax Plan

Wednesday morning, Fox News predicted a wonderful new tax plan from the administration:

…long-awaited corporate tax reform plan on Wednesday, lowering the top income-tax rate for corporations to 28 percent from 35 percent while eliminating deductions.

Corporations with overseas operations would also face a minimum tax on their foreign earnings, new tax benefits would be given to incentivize U.S. manufacturers while taxes on oil and gas companies would reportedly see their taxes go up while losing many large deductions and subsidies.

Now we can see what President Obama actually is proposing.  Although he offers to lower the top corporate rate from 35% to 28%—and that’s the headline—the proposal represents a net tax increase.

Moreover, he wants to make permanent his tax credits and other subsidies for his favored “green” energy products; although in a cynical offering to conservatives, the proposed Obamatax also contains the Santorum manufacturer’s tax subsidy.  Obama never seems to understand that if a product, company, or industry can’t compete on a level playing ground—in an actual free market—that product, company, or industry isn’t ready for market at all.

Along these lines of special treatments according to whether Obama approves or disapproves of an industry, the Obamatax would eliminate oil and gas tax preferences (while maintaining those “green” subsidies).  This, though, will drive up gasoline prices and home (and business) heating costs—and those manufacturers’ energy costs—to the detriment of our struggling economy and of the Americans trying to get by in it.  Despite this, the subsidies should, indeed, be gotten rid of, but the “green” subsidies should be eliminated, too.  With a truly level playing field, the effects will spike and ripple quickly, and costs ultimately will stabilize at lower levels from the overall simplification and the lack of “green” costs being absorbed by the oil and gas—and all other—industries and energy consumers.

The Obamatax applies a tax to business’ overseas profits, a first in American history—and a dramatic increase in the taxes owed by American businesses.  The administration justifies this with claims like:

If foreign earnings of U.S. multinational corporations are not taxed at all, these firms would have even greater incentives to locate operations abroad or use accounting mechanisms to shift profits out of the United States[.]

On the other hand, Intel, just to take one example, earns 85% of its revenue from its overseas computer chip and other manufacturing facilities—facilities that are devastatingly expensive to build or operate here.  Now Intel’s overseas profits will be taxed.  Since Intel makes its money overseas, though, why would it want to remain a US-headquartered corporation under the Obamatax regime?

There’s also the small matter of who gets this tax “cut.”  It isn’t the sole proprietorships, partnerships, Subchapter S, and so on firms whose profits are passed on to the business’ owners, who then pay ordinary income taxes on that passed through income.  Obama’s own IRS data indicate that over half of American business income is earned by these “noncorporate” companies.  But that needn’t concern an administration bent on raising taxes any way it can get away with.

True to form (this form is not unique to the present administration), the Obamatax dictates to businesses what their policies and paradigms must be.  It intends to eliminate “last in first out” accounting, disallow the use of life-insurance policies as a tax shelter, tax carried interest as ordinary income, and eliminate depreciation for corporate aircraft (this last is chump change, but it’s an important bone for the President’s base).  Even more intrusively, though, the Obamatax interferes with debt financing decisions by reducing the deductibility of interest on business’ borrowings.

There’s the underlying mindset, too.  The Obamatax justifies the “minimum tax on foreign earnings” by saying it would

discourage a global race to the bottom in tax rates.

as if low taxes, or having the lowest taxes globally, is somehow bad.  As if it’s really the government’s money, and they’ll magnanimously let our companies have what government deems appropriate.

In touting this tax change (it’s hardly a reform), Secretary Geithner said that the overhaul should be fiscally responsible (the Obama definition of “responsible,” of course) and,

A key test of any reform should be whether the net impact of the changes improves the incentives for investing in the United States.

If he really meant that, why is this the proposal?  Answer: he really does believe it; the proposal’s structure simply displays, again, the administration’s breathtaking lack of understanding of economics.

Obama is masquerading this as a tax cut, but it’s plainly another of his tax increases, and it’s commensurately hard on our already weakened economy.  It’s a good idea to lower the tax rate, and it’s a good idea to eliminate (though reductions are a good start) tax credits, loopholes, subsidies, and the like.  But these must be across the board—no company or industry should be getting special government treatment, good or bad.

A Look at our National Debt

The Congressional Budget Office pipes up.  Here’re some highlights from its January 31 annual Budget and Economic Outlook.

The current-law baseline which the CBO uses is a set of budget projections based on existing law as enacted, including sunsets and expirations.  These assumptions thus accept, for instance, that all temporary tax provisions, including those originally enacted as part of the Economic Growth and Tax Relief Reconciliation Act of 2001 and the Jobs and Growth Tax Relief Reconciliation Act of 2003—the Bush tax cuts—will expire as scheduled and that the alternative minimum tax (AMT) will not be indexed for inflation past 2011.  Further, under these baseline assumptions, about $1 trillion of spending cuts that mandated under the Budget Control Act of 2011 following the failure of Congress’ supercommittee will begin as scheduled in January 2013.

What flows from this baseline?  The budget deficit falls from the current year’s nearly $1.1 trillion, or 7.0 percent of GDP, to 1.5 percent of GDP in fiscal 2015—primarily due to an optimistic 25 percent increase in total federal revenues during that period.  The CBO cautions, though, that the deficit will resume its expansion post-2015 due to mandatory spending on programs such as Social Security, Medicare, and Medicaid and increasing interest payments on the still expanding federal debt.

The CBO also offered estimates based on an alternate scenario and its assumptions.  In its “alternative fiscal scenario,” the CBO assumes that the expiring Bush tax cuts are extended (excluding the current 2% payroll tax holiday); the AMT is indexed for inflation post-2011; Medicare physician payments are held constant at current levels (rather than falling nearly 30 percent in March 2012); and the spending cuts required under the Budget Control Act do occur.

Using these assumptions, the CBO concludes that annual budget deficits will remain elevated at about 5.4% of GDP over the next 10 years, and the ratio of publicly held debt to GDP will rise from its current elevated level of nearly 72% in fiscal 2012 to over 94% in fiscal 2022.

There are other aspects to this.  The CBO estimates that with the Bush tax cut expiry, economic growth—GDP growth—will be a meager 1.1% until recovery can begin in the out-years.  On the other hand, were these alternate assumptions enacted, GDP growth would be 0.3 to 2.9 per centage points greater than under current law.  Later in the decade, though, higher levels of government borrowing would crowd out private investment, drive up interest rates, and hold back economic growth.

Notice what’s not being assumed in the alternative scenario: real cuts in spending.  The assumptions don’t even include the effects of the fictional cuts of “reduced increases” in future spending.  What is it that drives that “higher level of government borrowing?”  It’s not not enough revenue for the government.  It’s too much spending by the government.

When, and only when, government spending is reduced to sane levels can we begin to pay down our burgeoning national debt.  Only by leaving our money in our hands and not having it taken away from us by ever-increasing taxes and by ever-increasing debt payments can our private investments increase, our job creation increase, our prosperity begin to recover.

h/t: Deloitte