
Teaching Opportunity Successfully Avoided

Because safe spaces are more important than education spaces.

A Virginia school district has “temporarily” banned the classics, The Adventures of Huckleberry Finn by Mark Twain and To Kill a Mockingbird by Harper Lee, after a parent complained that her high school-aged son was traumatized by racial slurs used in the books.

Would a trigger warning have helped this snowflake masquerading as a Mom to do her job as a parent?  Probably not:

I keep hearing, “This is a classic, this is a classic[.]”  …  I understand this is a literature classic.  But at some point, I feel that children will not—or do not—truly get the classic part—the literature part, which I’m not disputing.  This is great literature.  But there are racial slurs in there and offensive wording that you can’t get past that.

No, the children can’t.  Not when their parents won’t let them learn how to do so.  And: I read Huck Finn in junior high and Mockingbird as a high school sophomore.  The slurs, aside from being part of the stories—they were, after all, tales of their times, another aspect of this teaching opportunity away from which this school, this “parent,” slunk away—they were minor incidents in the tales.

And: if these minor parts of the tales really are that important to today’s youth, to today’s infantile parents, then how better to teach these children how to deal with the slurs, the racism, the ugliness that still exists, for all the progress we’ve made since those days when I read this stuff without a hazmat suit to protect me, than to do it in a controlled environment where such words can be put in the contexts of their times and then in the context of our times?

The alternative, after all, is that these children will eventually leave their safe space homes and their safe space schools and encounter such behaviors out in the world without having had a chance to learn how to deal with them.  Then these children will learn how badly cheated they’ve been by those whom they thought they could trust because those homes and schools were not even close to safe because of “safe” space shielding.
Some Context For The Latest Headline Unemployment Rate

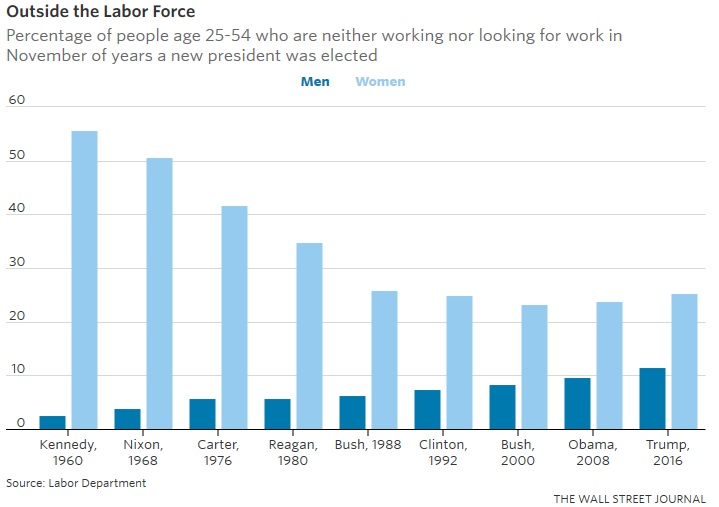
Here are some graphs, via The Wall Street Journal, that show why that headline rate of 4.6% isn’t all it’s cracked up to be.outdidelaborforce

The WSJ emphasized two points here, aside from the fact that this age group being outside the labor force has nothing to do with retirement or being in school:

First, a small but ever growing minority of 25-54-year-old men are no longer in the labor force. In the 1960s, just 2.7% of men that age were outside the labor force. As of November, it’s 11.5%.

Second, from the 1960s to late 1990s, 25-54-year-old women became less and less likely to be outside the labor force (this is primarily driven by a decline of stay-at-home mothers, as more women took jobs). But in the last 15 years, the share of women outside the labor force has been growing too. It’s now up to 25.3% from 23.2% in November of 2000 just before George W. Bush took office.

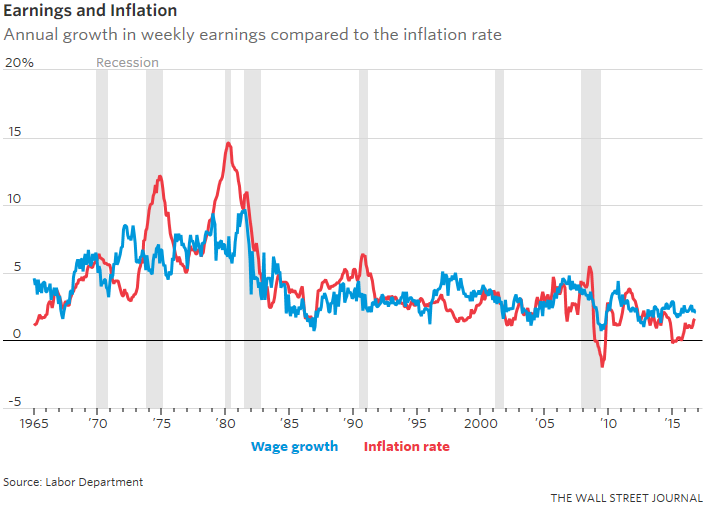
Which might contribute to and why, perhaps, there’s so little wage growth, as shown in this graph:wagegrowth

There’s just too much slack in the population’s ability to work.

Four Pillars of a Health Care System?

The Wall Street Journal posited this in a Wednesday op-ed.

1. Provide a path to catastrophic health insurance for all Americans.

The WSJ then supports this with old saws: being covered generally leads to better medical results, health insurance is good for the wallet, and so on.  Then they want a government solution—while they carefully avoid saying how they would pay for it:

The ObamaCare replacement should make it possible for all people to get health insurance that provides coverage for basic prevention, like vaccines, and expensive medical care that exceeds, perhaps, $5,000 for individuals.

Those Americans who don’t get health insurance through employers, or Medicare and Medicaid, should be eligible for a refundable tax credit….

They don’t even say why catastrophic health insurance should be particularly targeted by Government.  They ignore an actual market solution for this: free market competition, accompanied with lower tax rates (which leave more money in people’s pockets), and no annual or income caps or requirements for high deductible insurance plans (and no requirement for any insurance plan at all) on Health Savings Accounts.  Folks are fully capable of making their own decisions about the structure of their health insurance plans without the Know Betters of Government holding them by the hand.  And insurance companies, in a fully competitive environment, are fully capable of developing and delivering the products actual customers want without Government mandates.  If that includes catastrophic insurance plans, those will appear.

2. Accommodate people with pre-existing health conditions.

See above regarding free markets.  Of course such coverage would come at a higher cost than other sorts of health coverages; the risk being transferred to the insurer is higher.  But even this risk is not certain.  Folks who’ve had a heart attack (or more than one), for instance, have a preexisting condition (unless a single heart attack has occurred sufficiently far in the past that a medical doctor (the patient’s, not the insurer’s or a Government hireling) says it’s a one-off and not preexisting), but not everyone who’s had heart attacks will have their next one simultaneously.  Even a preexisting condition can be amortized across time given a free market that allows pooling of [those who’ve had heart attacks] so that premiums can be adjusted to match the actual payout requirements, the actual risk—just like “ordinary” insurance plans.

So as long as someone remains insured, he should be allowed to move from employer coverage to the individual market without facing exclusions or higher premiums based on his health status.

This conflates two separate questions.  The preexisting question is addressed just above.  The mobility of an insuree (or someone who’d like to buy a health insurance plan) is separate: and yes, in a free market environment, an insuree would be able to take the plan he’s purchased, whether originally obtained through his employer (unless it was the employer who actually did the purchase and the premium payments) or bought on the individual market, with him wherever he went or to whatever job he moved.  The latter case, too, would reduce or eliminate the need for the new employer to offer health insurance coverage through his benefits program.

3. Allow broad access to health-savings accounts.

There should be a one-time federal tax credit to encourage all Americans to open an HSA and begin using it to pay for routine medical bills. And HSAs combined with high-deductible insurance should be incorporated directly into the Medicare and Medicaid programs.

Another Government solution—again carefully unpaid for—and it’s much too timid.  I addressed HSAs and their market availability above.

4. Deregulate the market for medical services.

This is the only move necessary.  It’s the move to enable the free market solution.

Full stop.

Obstruction

With full control of Congress and the White House, Republicans have anticipated being able to repeal the law using a special budget maneuver that would allow them to get around a filibuster by Democrats in the Senate.

Yes and no.  The budget maneuver is reconciliation, and it’s usable only on budget matters.  That means that Obamacare will be defunded pretty straightforwardly, but the law itself still will be on the books—for a future Progressive-Democratic Party-controlled Congress to re-fund using the same budget reconciliation maneuver.  The law itself needs to be fully repealed, too; defunding it can only be a stop-gap measure.

Eight honest Progressive-Democrats are going to have to find the moral courage to step up and support actual repeal.

And there’s this.

[T]o replace it, they likely would need the support from eight Democrats and all 52 Republicans in the Senate (if Republican John Kennedy wins a December 10 runoff in Louisiana) to reach the 60 votes needed to clear the chamber’s procedural hurdles.

That procedural hurdle is the filibuster.  For this, too, eight honest Progressive-Democrats are going to have to find the moral courage to step up and support replacement with legitimate health insurance market paradigms.

Fat chance, but the fight needs to be carried out loudly, with no room for Senate Progressive-Democrats to hide behind their excuses and their crocodile tears over Americans being too stupid to take care of themselves and so need these Know Betters to do for them.

Senate Minority Whip Richard Durbin, a Democrat from Illinois, predicts Republicans will have difficulty passing a replacement health law.

Yup.  Look for continuation of Progressive-Democrats’ past six years of obstructionism into the next two or more years.

The Diversity Officer Doesn’t Understand

Recall the Somali student at Ohio State University who attacked so many of his fellow students because he blamed the US for anti-Muslim fervor in Burma and who “wanted to kill a billion infidels.”

Stephanie Clemons Thompson, Ohio State University’s Assistant Director of Residence Life, put this up on Facebook, according to Debra Heine of PJMedia:diversityofficercompassionHeine has already addressed the pain of his fellow students whom he attacked and other of his fellow students, pain which Thompson has chosen to ignore.  I’ll just note that Thompson plainly does not understand family, community, association.

Artan removed himself—no one removed him—through his own criminal acts from his earlier status as a Buckeye, from his membership in the OSU family, from his membership in the community of the United States.  He created himself an outlaw.  Thompson should review her Locke, which she surely read in her own freshman General Studies coursework.

Oh, and Thompson appears to have taken down her Facebook post.  Apparently she doesn’t even have the courage of her own conviction.