
Personal Health Information Security

We’ve had HIPAA—the Health Insurance Portability and Accountability Act—for nearly 20 years. This act requires, among other things, all handlers of our personal medical information (primarily, but not exclusively, our doctors, hospitals, and health coverage plan providers) to have our permission to pass that information along, even to other doctors, hospitals, and health coverage plan providers and to take adequate steps to safeguard that information when it’s in their hands or being passed along.

It seems that this administration doesn’t consider itself bound by that same law. The latest example of this evident lawlessness is ObamaMart. The GAO has completed its own assessment of ObamaMart’s security and security practices, and it’s unimpressed.

…weaknesses remained in the security and privacy protections applied to HealthCare.gov and its supporting systems.

This is a year after ObamaMart’s rollout and the discovery of its lack of security. This is four years after HHS, through its CDC, began developing ObamaMart and…testing…it. It boggles my pea brain that security problems of this magnitude could still exist.

In the report, the GAO makes six recommendations to the Department of Health and Human Services to implement security and privacy controls to protect sensitive material. The report also makes 22 recommendations to resolve technical weaknesses in security controls.

Problems with the site ranged from the agency not setting up an alternate processing site for HealthCare.gov systems to allow them to be recovered if the site was hacked or went down to the strength of passwords.

These are basic things that any Computer Science 101 freshman knows. But wait—there’s more.

In addition to these weaknesses, we also identified weaknesses in security controls related to boundary protection, identification and authentication, authorization and configuration management. Collectively, these weaknesses put HealthCare.gov systems and the information they contain at increased and unnecessary risk of unauthorized access, use, disclosure, modification, or loss.

These are more of those things any freshman learns. And these are more of the sorts of things that HIPAA was designed to protect.

The HHS has denied some of these problems exist.

HHS has agreed with three of the six recommendations and has agreed with all 22 technical recommendations.

This isn’t incompetence. These folks are extremely intelligent and talented. Nor is this laziness. These folks are among the hardest working in government. No, this shortfall was deliberate.

Among the issues that concerned the administration’s own technical experts at the time was that security testing could not be completed because the system was undergoing so many last-minute changes.

Because securing citizens’ personal information is only an afterthought to this administration. Because obeying the principles and spirit of HIPAA and related Federal laws, if not their letter, just doesn’t matter to this administration.
Obamacare, Errors, and Attitudes

The AP has an article that goes into the pitfalls and pratfalls that Obamacare faces this fall, 2014 enrollment period. I’m interested in one error in particular and the attitude of one Democrat in particular who voted for Obamacare’s passage.

The error was the overpayment by the Federal government of many of the subsidies it handed out to…defray…the premium costs of having an Obamacare health plan. Overpayments could occur from a plan buyer underreporting income, from ObamaMart not correctly matching income data with subsidy accruals, and so on.

As a result of having discovered those overpayments, the government is trying to recoup them from the recipients. Congressman Bill Pascrell (D, NJ) disagrees with making people pay back part of their premium subsidy.

Why should individuals be punished if they got a bump in salary? To me, this was not the ACA I voted on.

Indeed, why should individuals be punished? Yet they would be, if Pascrell’s attitude prevails, by paying out more subsidy than was due. Oh, wait, the individuals being punished are taxpayers.

Of course Pascrell (and his fellow Democrats) know this; they just don’t care about those individuals. Taxpayers, after all, are just money trees with which to fund Democrats’ voters.

Doesn’t College Cost Enough Already?

In an effort to combat the high cost if college, the Obama administration thinks it’s appropriate to make borrowing easier.

Under a plan likely to take effect next year, the Education Department would check the past two years of a borrower’s credit, instead of the current standard of five, for blemishes such as delinquencies or debts in collection. Also, any delinquent debts below $2,085 would be overlooked; currently, delinquencies of any amount are grounds for rejected applications.

I’ll leave aside the increased pile of loans for those who least can afford to borrow, and the increased risk of default from that; these questions are addressed in that Josh Mitchell article in The Wall Street Journal that’s on the other side of the link above.

There’s another problem that’s not addressed, either in the article or by the Obama administration.

That problem is a well-known one, except apparently in Liberal circles: subsidizing a thing increases demand for it. And if supply can’t keep up with that increased demand, the price of the thing goes up. A lot.

Making borrowing for college easier will stimulate demand for college. Since the availability of college can’t rise as quickly as that demand, the only outcome is…a large increase in the price of college. This is an increase, too, that’s actively abetted by college administrators, as Professor Peter Wood noted ‘way back in 2005:

Tuition is set high enough to capture those funds and whatever else we think can be extracted from parents. Perhaps there are college administrators who don’t see federal student aid in quite this way, but I haven’t met them.

Wood was talking, at the time, about Federal student subsidies, but his remarks apply just as surely to Federal efforts to make more money available to colleges via easier to get loans like these.

Scottish Independence

The view of a poor, dumb colonial.

Suppose the Scottish referendum next week goes in favor of independence. What would be next for Scotland?

Among the complexities of separation is the matter of pensions provided by employers. Most such pensions are not fully funded; although, most such pension providers have apparently viable plans for curing the shortfall, over some number of years. However, the EU (and we’ll assume Scotland succeeds in joining the EU for this bit) requires all pension funds with members in two or more countries to be fully paid up. Moreover, funds that are not have only two years to get fully paid up. There are quite a number of large-ish UK companies, employing thousands each, whose pension funds have members in both countries, and whose pension funds are on one of those “some number of years to fund” plans.

There’s some chatter in the UK about splitting the pensions in two, one for the UK and one for Scotland, as a means of ducking this problem. I see a possibility of splitting the companies themselves in two, each with its own pension scheme. Either course, though, is fraught with complexity.

A larger complication is the UK national debt, some £1 trillion ($1.62 trillion): how would this be divided, and based on what criteria? I’ll elide whether the new Scottish economy could handle its new debt.

That sort of thing is trivial, though, compared with a couple of larger questions. Scotland has some serious economic problems, including that debt, a risk of sharp inflation, lack of clarity on what it would use as a currency, what sort of trade arrangements a settled-on currency would imply, and so on.

The economic problems will have their impact on independent Scotland’s near- and mid-term stability.

Too, accession to the EU requires a unanimous vote of the existing members, and that’s not a done deal. Which means Scotland would not be able to count, soon, on any EU…assistance.

Frankly, I think Scotland would be better off outside the EU than in it (recall the EU’s treatment of Ireland and Iceland), but this is a move Scotland has to make, and properly so, without my sage advice.

Regardless of EU membership and those “larger problems” just mentioned, though, independent Scotland will need to broaden its economy. 80% of its national income is from North Sea Oil which, aside from questions of how to divide that with the UK, is a declining asset value [sic], and the bulk of the remaining 20% is from tourism. A self-sustaining independent Scotland will need a more broadly based economy in order to function without the UK subsidies it currently gets.

Finally, I don’t know that Scotland would be better off independent from the UK. Certainly, there are advantages for a nation that’s free to chart its own course without having to say, “Mother, may I” to a higher-up. I think, though, given Scotland’s socialism and those subsidies, the UK would be better off with an independent Scotland.

The aftermath also will be fun to watch. Northern Ireland? Catalonia? Basque Country? Sicily?

Obamacare and Health Coverage Cost Growth

President Barack Obama promised us, all those years ago, that if only Obamacare were enacted, a family’s health plan premium would drop by $2,500 per year, and no one would lose their employer-provided health plan. Period.

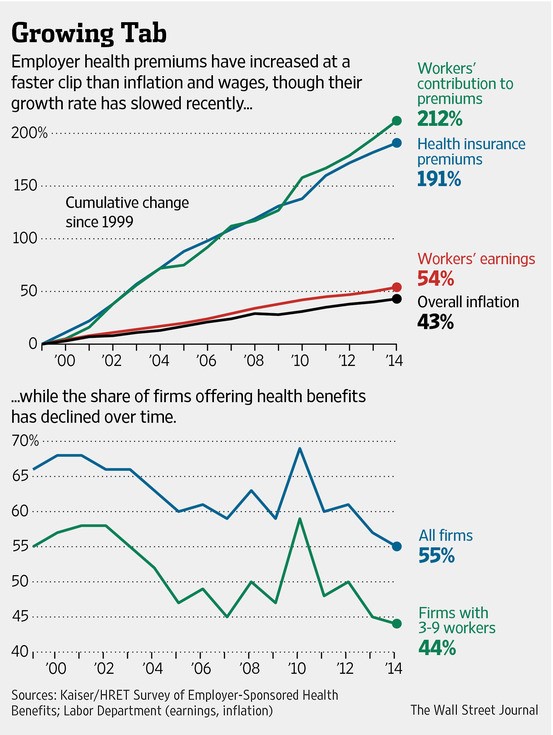
These two graphs from The Wall Street Journal draw a different…picture.ObamacareCost

These graphs cover the period since 1999. As the upper graph shows, the premiums for employer-provided health insurance and, since Obamacare’s passage in 2010, for employer-provided health plans, have risen at a steady pace—unchanged by Obamacare, and specifically, no drop in premium cost. It’s the same with the employee’s share of those premiums; that share’s pace of increase also has been unaffected—that is, no drop in cost—from Obamacare.

Now look at the lower graph. After spiking in Obamacare’s year of enactment in 2010, the per centage of businesses offering health plans to their employees has fallen to the lowest level in the 15 years depicted.

At best, Obamacare isn’t lowering employer-covered workers’ health coverage costs. There has been, though, a sharp decrease in the number of folks even offered employer-provided plans.

(That wages have risen much more slowly than health plan premiums is a different subject.)