Whitewash

It seems the Federal Reserve knew of the risks stemming from SVB management moves as long ago as 2019 [emphasis added].

In January 2019, the Fed issued a warning to SVB over its risk-management systems, according to a presentation circulated last year to employees of SVB’s venture-capital arm….
The Fed issued what it calls a Matter Requiring Attention, a type of citation that is less severe than an enforcement action. Regulators are supposed to make sure the problem is addressed, but it couldn’t be learned if the Fed held SVB to that standard in 2019.
…
Following the 2019 warning, the Fed informed SVB in 2020 that its system to control risk didn’t meet the expectations for a large financial institution, or a bank holding company with more than $100 billion in assets, the presentation to employees at SVB’s venture-capital arm said.

And:

Over time, the central bank issued numerous warnings to SVB, suggesting the bank’s problems were on the radar of the Fed, the bank’s primary federal regulator.

So, what was done by the Fed’s regulators in response to this string of noncompliances?

A central-bank review of its oversight of SVB is due by May.

Will those prior whitewashes be followed up with an official whitewash?

I’m not holding my breath over a favorable outcome, which IMNSHO would include, at the very least, the public firing for cause of the Fed regulator(s) directly responsible for SVB oversight and that individual’s/team’s supervisor. Pour l’encouragement des autres régulateurs.
Trademark Whining

Jack Daniels has a trademark beef in front of the Supreme Court.

Phoenix-based VIP Products markets dozens of novelty pet products, including the 18-inch “Bad Spaniels” vinyl toy shaped like a liquor bottle, advertised on its website as “Silly and Fun For Everyone!”

Jack Daniels summarized its beef:

Jack Daniel’s loves dogs and appreciates a good joke as much as anyone. But Jack Daniel’s likes its customers even more, and doesn’t want them confused or associating its fine whiskey with dog poop[.]

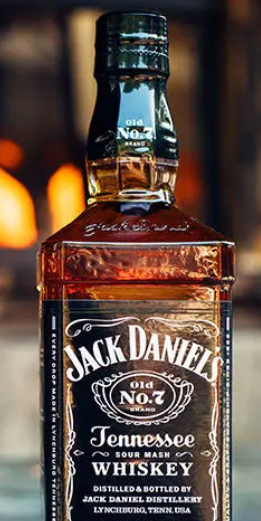
This is what a Jack Daniels whiskey bottle looks like:

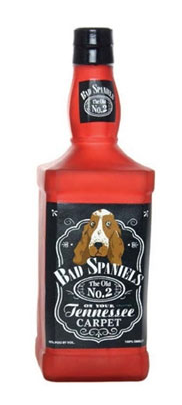
This is what VIP’s Bad Spaniel chew toy looks like:

Jack Daniels thinks that toy, a dog’s plastic chew toy, looks too much like its own liquor bottles and that its customers would be confused.

It’s interesting and amusing—and maybe insulting its customers—that Jack Daniels thinks its customers would be so easily confused between a liquor bottle and a dog’s chew toy.

No Chief Risk Officer

That’s what Silicon Valley Bank had for the last 8 months of 2022. Much is being made of SVB’s choosing to employ a Diversity, Equity, Inclusion person in an executive position during that time frame, but a more important function is being missed in this kerfuffle. That is the answer to this question:

It is not clear who handled [SVB CRO until April ’22, Laura] Izurieta’s duties in the last eight months of 2022.

SVB has a President, a Chief Credit Officer, a Chief Operations Officer, and a Chief Auditor. Each of those persons are, or should have been, fully capable of assessing the level of interest rate risk involved with the interest risk of the bank’s holdings with the Fed vs the interest rates it was paying its depositors.

Each of those worthies are, or should have been, fully capable of assessing the demand and cash flow risk associated with the concentration of particular categories of depositors—startups and venture capitalists—with intrinsically very high cash flows and so high rates of cash deposits and withdrawals compared with “ordinary” consumer depositors’ rates of deposits and withdrawals.

Each of those persons are, or should have been, fully capable of assessing the amount of cash held in accounts above the FDIC-insured maximum of $250,000 compared with the amount held in accounts smaller than that limit. Each of those persons are, or should have been, capable of assessing the closely related risk from the degree of concentration of those large accounts in the hands of a relative few account holders and so the risk of any one of those holders withdrawing all of their money.

The presence of a CRO on the payroll and on duty would have been the one to concentrate on those risks, freeing the rest of SVB’s management team to concentrate on other areas, but management, for one reason or another chose not to employ one for those critical eight months. And that management team failed to pay attention, chose not to pick up the slack.

An Attack on Workers’ Rights

Hypocritically, it’s by the Progressive-Democratic Party, which runs Michigan’s government. That’s the party that claims to champion the rights of America’s workers.

[State] Senate Democrats voted along party lines in support of repealing the decade-old “right-to-work” law in a state long considered a pillar of organized labor.

The State’s House already had passed a substantially similar bill, now the two go to conference to reconcile the differences, then the result will be voted up in both houses and sent to Governor Gretchen Whitmer (D) to be signed into law.

Michigan’s workers, for the last decade, had been able to speak for themselves, to join or not join unions, to not pay dues to unions to which they didn’t belong.

The Michigan government is telling those workers they have no voice, and their wishes have no importance. Oh, and pay up, suckers.

So much for workers’ rights when Progressive-Democrats reign in Michigan.

Balancing Act

That’s what conventional “wisdom” says confronts the government of Australia as it contemplates buying nuclear-powered submarines from the US. The buy is part of AUKUS’ combined effort to counter the People’s Republic of China’s military buildup and its continued strengthening of the PLA in the PRC’s occupation of the South China Sea.

Australia is trying to strike a balance between its close relationship with the US and its ties to China, which buys much of its valuable iron ore and is its largest trading partner.

There’s nothing to balance here. There are lots of nations, all over the world, with an interest in buying Australian iron ore, Australia’s iron processed from that ore, such steel as Australia chooses to produce. There is a wide world of existing and potential trading partners for Australia’s other goods and services. Shipping need not be that expensive, either: the nations metaphorically next door that rim the South China Sea, the Republic of China, the Republic of Korea, and Japan all have need of iron ore and iron and are interested in the plethora of additional goods and services that Australia might sell.

Australia has no need of the PRC’s market, and the sooner it divests itself, the sooner it will shake its dependency on and pressure from the PRC.