
Change We Can Hope For

A post-World War II-era program that forces raisin producers to give part of their annual crop to the government could soon be a relic of history.

Several Supreme Court justices expressed doubts Wednesday that federal officials can legally take raisins away from farmers without full payment even if the goal is to help boost overall market prices.

An immediately post-war New Deal law allows the Federal government to manipulate the market’s raisin supply by seizing a significant fraction of a raisin farmer’s crop and thereby prop up raisin prices—for the benefit of that farmer, you see.

Raisin farmers, over the specific period at issue (because law suits, quite properly, have to be specific in their allegations), were required to give up 47% (!) of their crop to the Feds. Marvin and Laura Horne were among the farmers so afflicted, and they demurred, refusing to give up their property, their raisins. For their effrontery, the Feds have fined them almost $700,000.

The law in question, though, is a follow-on from the Supreme Court’s earlier Wickard v Filburn case that gutted the Commerce Clause by allowing the Federal government to dictate to farmers how much wheat they could grow—and therewith to manipulate market prices. Wickard made possible all of the subsequent market interferences and farm diktats that the government has inflicted on the nation.

This case, Horne v Department of Agriculture, is an opportunity for the Supremes to begin correcting that original mistake.
Bailouts

The Inspector General for the Federal Housing Finance Agency (FHFA) recently reported that Fannie Mae and Freddie Mac might need more government bailouts if housing markets decline. The problem: lack of capital reserves to serve as a buffer against future losses.

That lack of capital, says Fannie Mae boss, Tim Mayopoulos,

increases the likelihood that Fannie Mae will need additional capital from Treasury at some point.

William Isaac, FTI Consulting Senior Managing Director (and former FDIC Chairman), and author of the piece at the link, has a solution: Treasury should stop sweeping Fannie’s and Freddie’s profits into the Federal government’s piggy bank. He’s right that this is illegal, but it’s the wrong solution.

The correct answer to the problems with Fannie Mae and Freddie Mac is not to bail them out in any way shape or form. The correct answer is to disband them completely, erase them from government, and replace them with…nothing. Full stop.

All the more Reason

…to speed reform of the way in which our economy produces medical care services and in which we pay for them.

[A] 66-year-old couple retiring this year with average Social Security benefits can expect medical costs to consume 67% of the Social Security they will receive in retirement.

A 55-year-old couple who plan to retire in 10 years can expect to devote about 90% of their lifetime Social Security benefits to healthcare costs.

There’s more:

Social Security benefits typically grow by approximately 2% a year—the overall rate of inflation. But medical costs in general tend to rise by more, 5% to 7% a year[.]

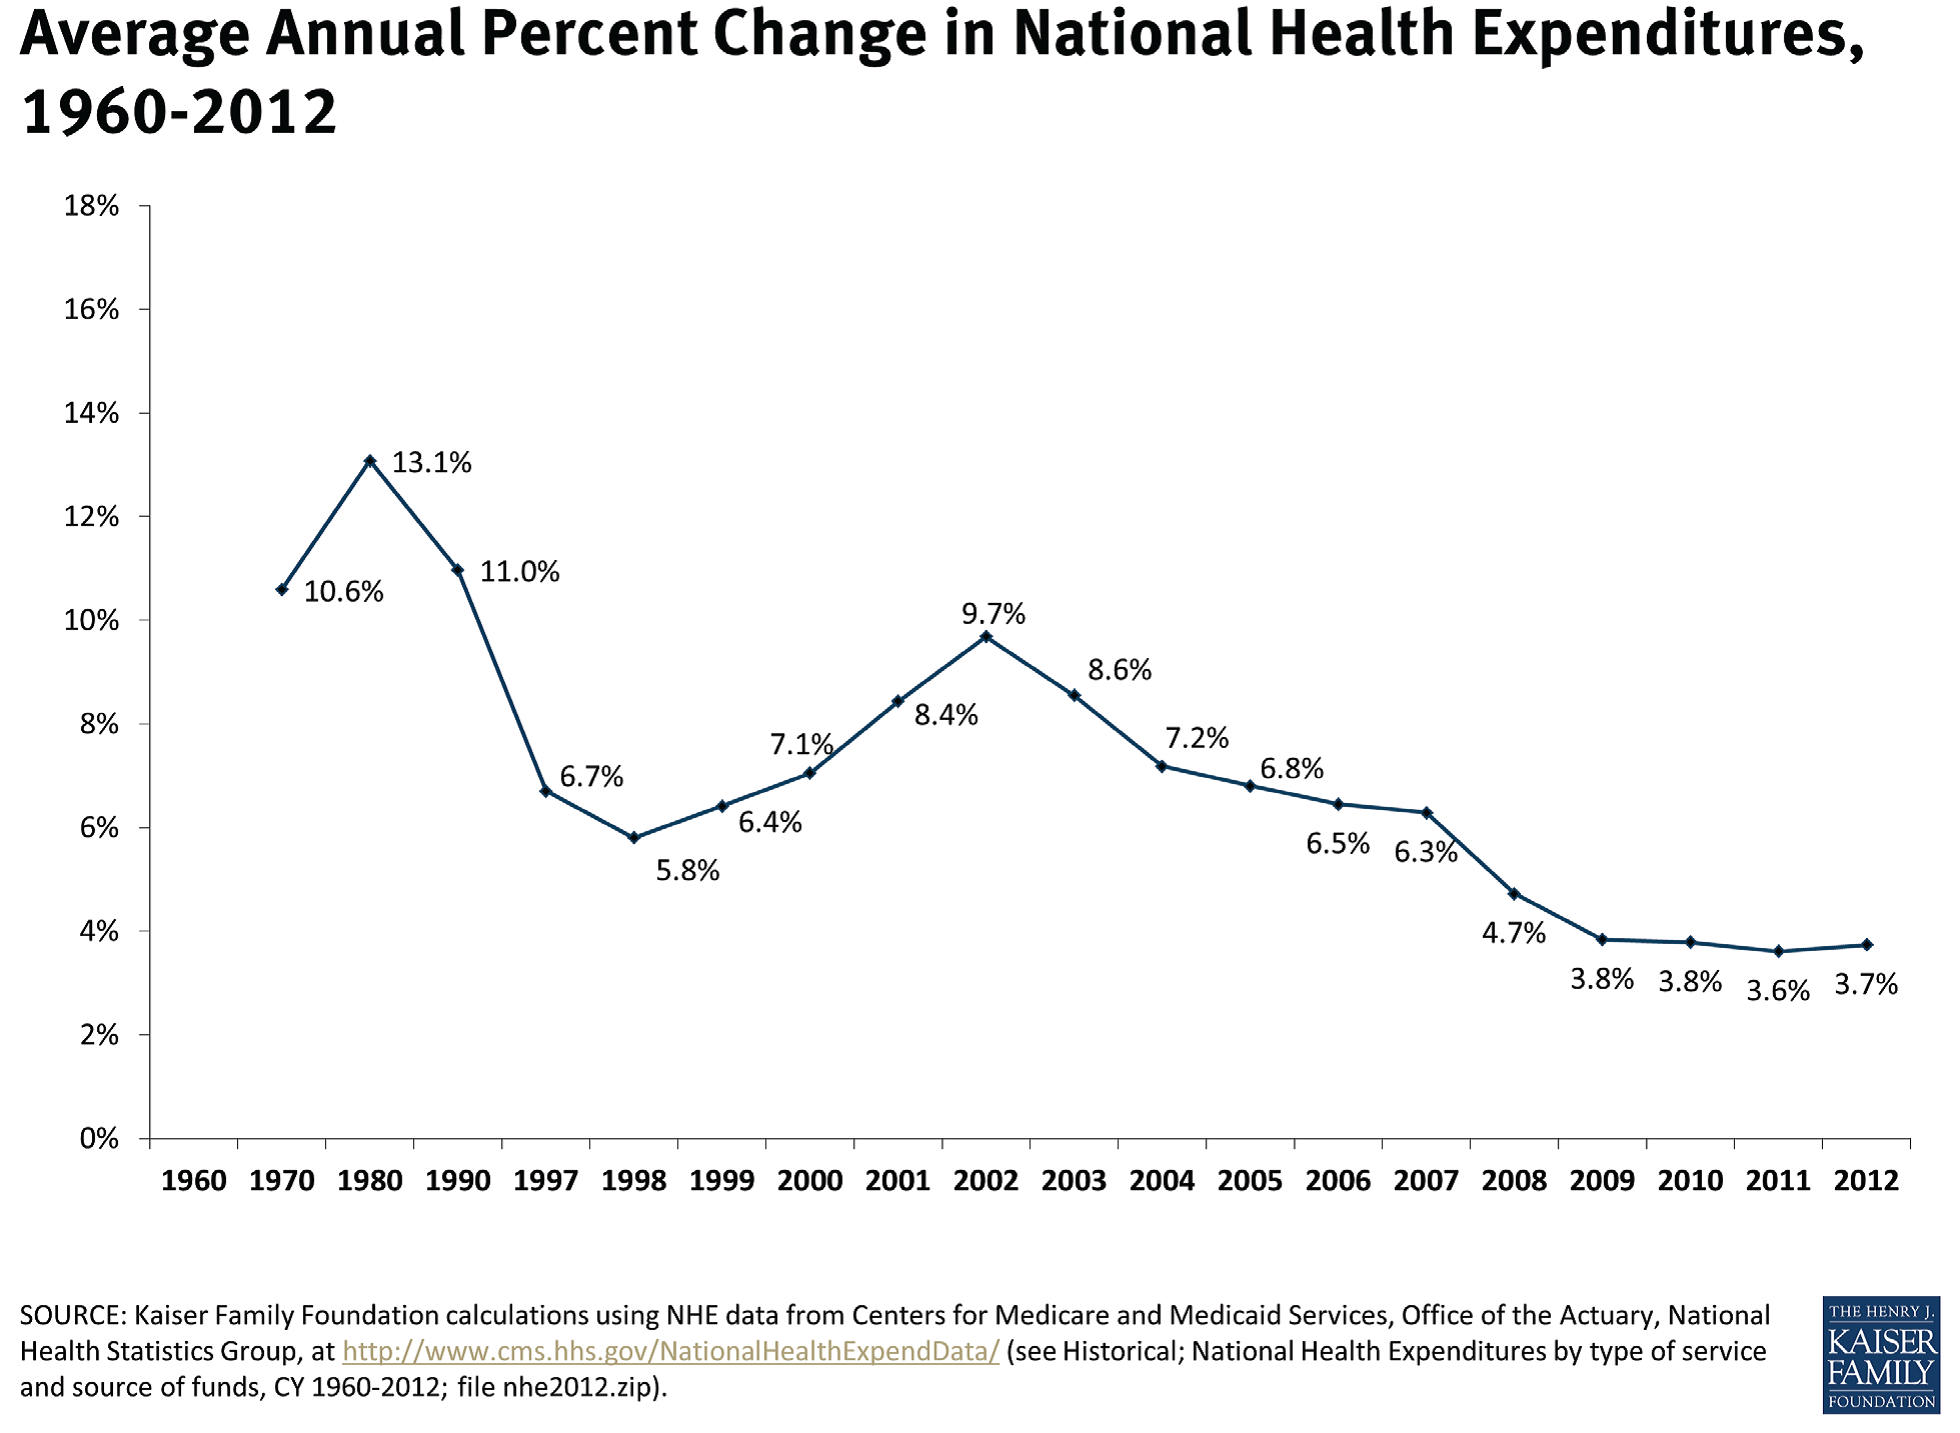
There’s this graph, too, that illustrate cost change trends since 1960:HealthCostTrends

Since Obamacare was enacted and has started to take effect (since 2010), the then-eight-year-old trend of decreasing costs has been completely stopped. That’s the effect of government intervention into a free market.

If we’re to correct this, if we’re actually to hold down, not just the rise in costs, but the actual costs themselves, we need to get government out of the way and use free market solutions: get rid of the health welfare that is Obamacare, allow insurance companies—which would sell true insurance policies—to charge premiums based on the actual risk transferred from customer to company, and allow insurance policies to be sold across state lines—that is nationwide.

All government intervention succeeds in doing is preventing competition and market forces from reducing and then holding down costs. Which hits hardest the very people these government programs are claimed to help.

There’s More To It

…than this, or so it seems.

A wave of cash is leaving the eurozone, where returns on safe assets are infinitesimal, if they are positive at all, and headed to the US and other refuges such as Denmark and Switzerland.

Europe’s common currency has fallen 22% against the dollar in less than a year, from $1.39 to $1.08. The euro touched a 12-year low of less than $1.05 this month.

Returns on safe assets are infinitesimal in the US, too, with the Fed still actively suppressing interest rates (to the detriment of those Americans dependent on fixed income assets, but that’s another story). Why, then, would money come to the US at the expense of the eurozone—at the expense of the EU?

For one thing, we’re absolutely politically stable, our problems with the present administration (and the Left’s with the previous one) notwithstanding. So, in fact, are the EU and the eurozone subset of it. Here, though, there’s a growing possibility of Greece leaving, and fear that that will spark a cascade; there’s no possibility of, say, Texas leaving the US.

For another, the currency flow tends to become a self-fulfilling prophecy. As money leaves the euro for the dollar, demand for euros falls and for dollars rises, causing the price for euros to drop and for dollars to rise. The increasing disparity in value spurs more movement from the falling value asset to the rising value asset.

The stronger reason comes from where the money is going when it arrives in the US (or Denmark—an EU member, but not part of the eurozone—or Switzerland). Tommy Stubbington, in his Wall Street Journal article at the link noted that much of the flow into the US is going to US Treasury debt instruments: the constituent nations of the eurozone aren’t issuing government bonds at any sort of rate, so their price is relatively high, with those infinitesimal yields. The central banks of euro recipient nations like Denmark, too, are busily lowering national interest rates in an attempt to discourage everyone else from “piling into the krone.”

But the money also is going into equities. The US stock market is the largest, most active in the world, and it’s the least regulated, especially compared with the EU. Given a desire to leave the euro, there’s just no place for the money value to go besides our stock market (another reason for the market’s ongoing rise despite our underlying economy’s ongoing doldrums) and our treasuries. The latter which also helps the Fed get away with suppressing interest rates.

So why Denmark and Switzerland at all? They’re safe places for Europeans to keep their money nearby.

Central Banks, Interest Rates, and Fear

The Fed is looking to start raising its benchmark interest rates “real soon now.” This is expected to inject fear into investors used for so long to being coddled and protected from uncertainty by an interventionist central bank.

Christine Lagarde, head of the IMF,

warned Tuesday that markets could be heading for a repeat of the 2013 “taper tantrum,” in which stocks fell and interest rates rose around the world as the Fed considered winding down its “quantitative easing” bond-buying program.

She went on:

I am afraid this may not be a one-off episode. The timing of interest-rate liftoff and the pace of subsequent rate increase can still surprise markets.

This is just foolishness. In a free market environment, surprise not only is normal, it’s the stuff of profit-making. It’s also how enterprises steal a march on their competitors and how startups successfully break into a heretofore stable market. It’s how consumers benefit from the newly available additional choice, the better product, the new idea, ….

Even the “taper tantrum” concern is foolishness. The only ones hurt by that were the investors throwing their tantrum. The stock market quickly returned to its longer term trend, and the tantrum didn’t last long enough to hurt the actual economy.

Surprise in the markets is not a problem for us investors; it’s only a problem for government bureaucrats so dependent on their precious rules. And for crony capitalists fearful of competition.