
Another Argument for Disbanding Fannie Mae and Freddie Mac

Fannie Mae and Freddie Mac on Monday announced details of a controversial plan to allow some first-time homeowners to obtain a mortgage while putting down just 3% of the price of the home.

We’ve not finished recovering from the Panic of 2008, and these entities want to resume an underlying component of the last housing bubble and burst that contributed so heavily to that.

But wait:

Fannie Mae said the loans that allow for 3% down payments will be held to the same eligibility requirements as other Fannie loans, including underwriting, income documentation and risk management standards.

That’s a low bar, indeed, as it was during the last bubble.

The problem here is not so much the high leverage of those loans, per se, as it is the lack of skin in the game—the lack of equity, or actual ownership, or what is there for the borrower to lose—a 97% borrower has in the home he’s buying. What does he lose when can’t—or decides he doesn’t want to anymore—continue paying down his loan?

Here’s Andrew Bon Salle, Fannie Mae Executive Vice President for Single Family Underwriting, Pricing and Capital Markets (you can tell he’s important to Fannie Mae from the length of his title):

This option alone will not solve all the challenges around access to credit. Our new 97% LTV [loan to value] offering is simply one way we are working to remove barriers for credit-worthy borrowers to get a mortgage[.]

Which, of course, is only loosely related to reality: if the borrower were credit-worthy, he would have the scratch to put down 10%.

The argument seems to be, also, that it’s too hard for a homeowner wannabe to raise 10% of the house’s purchase price. This, too, is nonsense. The homeowner just needs to save longer and with more diligence. Or look to buying a less expensive house. Or both.

Judgment like this demonstrates the need for these two agencies to disappear and to let the market determine the viability of mortgage packaging and peddling.
Massachusetts’ Native American Senator Elizabeth Warren Objects

The Democrat from Massachusetts is saying that

House Republicans were threatening to shut down the government if they didn’t get a chance to repeal part of the 2010 Dodd-Frank law.

What Warren objects to is a provision in the proposed House funding bill—which funds the entire government, mind you—that would “undo the Dodd-Frank provision that prohibited bank units within the federal financial safety net from betting on derivatives.” This is critical because only Progressives like Warren know how to run a bank, or any other private enterprise. We’re seeing today how well government-run (VA) hospital businesses are doing, how well government-directed medical practices are working out, how well government-mandated health coverage plan businesses are doing.

Americans for Financial Reform Executive Director Lisa Donner added this:

The section of Dodd-Frank that Congress is proposing to repeal was put in place to help prevent future bailouts of too-big-to-fail banks[.]

While carefully eliding the fact that other sections of Dodd-Frank guarantee taxpayer bailouts of too-big-to-fail banks by declaring them systemically important and so subject to government seizure and “correction” outside bankruptcy law.

Finally, the only ones talking about shutting down the government are the Democrats.

The Gruber virus is spreading rapidly. This would be amusing if it weren’t so tragic.

Obamacare and Doctoring

If you liked your doctor, you could keep your doctor. Maybe. If you were lucky, and your Obamacare Plan still had him on its cut-rate, cut-service list of acceptable (to the government) doctors.

Or, if you like the hospital that now employs him (which doesn’t guarantee you get to see him; the hospital will make that decision). After all, the government’s Obamacare

architects believe that doctors, to better bear financial risk, need to be part of larger, and presumably better-capitalized institutions.

Because, of course, these Progressive Democrats know better than doctors how to provide medical care, know better than you stupid voters how to choose doctors, and know better than either of you how to conduct the business side of any doctor-patient relationship.

In addition to that bit of Gruber-esque dishonesty and dark transparency, Scott Gottlieb, at the above link pointed out this consequence:

Local competition between providers, who vie to contract with health plans, is largely eliminated by these consolidated health systems. Since all health care is local, the lack of competition will soon make it much harder to implement a market-based alternative to ObamaCare. The resulting medical monopolies will make more regulation the most obvious solution to the inevitable cost and quality problems.

This is not at all an unintended consequence. Aside from Democrat disdain for free markets and competition, it’s long been an open goal of the Democratic Party to move our health coverage and our health provision industries into a one, linked, single-payer program—carefully run by government for our benefit, of course.

Start queueing up things to be remembered in 2016: the Democratic Party needs to be swept into history’s dustbin so this damage, among all of their other damage to our country’s weal and global standing, can be repaired.

The sweeping also should be presented as a warning to the Republican Party.

Meanwhile

I wrote earlier about one small subset of regulatory barriers to US investment. Here’s another side.

The Australian Business Review headline pretty much tells the story, and they stand in sharp contrast with the burgeoning US regulatory environment.

Indonesian President Joko Widodo Pledges to Cut Investment Barriers

And the lede:

The new leader of the world’s fourth-largest nation promised to move aggressively to lower barriers to investment and overcome decades of unmet potential that have left Indonesia lagging behind more dynamic Asian nations.

Recognizes the man himself:

…we need investment, we need investors, to boost our economic growth….

And lowering regulatory barriers is critical to that. Because prosperity.

More Thoughts on Minimum Wage

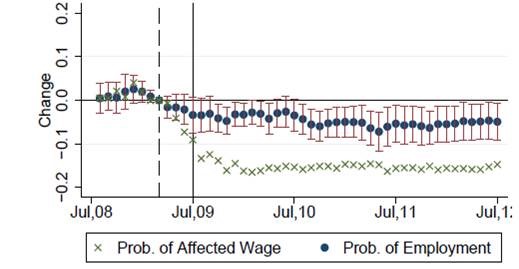
And actual data. Econbrowser pointed out a quasi-controlled study by PhD candidate Michael Wither and Professor Jeffrey Clemens that compared populations of workers in states that had minimum wage laws with higher minimum requirements than Federally passed wage requirements at the time the Federal legislation was enacted with populations of workers in states that did not. They also compared populations of workers starting out with wages higher than the new mandates with populations of workers with wages lower than the new mandates (workers with wages less than $7.50/hr and workers with wages between $7.50 and $10.00 at the time of a then-newly Federally mandated minimum wage of $7.25) over the three years following the Federal mandate.

This figure is from Econbrowser‘s summary of the study:ProbabilityOfEmployment

Dynamic estimates of the effects of minimum wage on low-skilled workers. Green x’s denote difference in probability of having a low-wage job between states with low minimum wages and those with high minimum wages. Blue dots indicate difference in probability of being employed between states with low minimum wages and those with high minimum wages, with accompanying 95% confidence intervals. Source: Clemens and Wither (2014).

In other words, a low-skilled worker in a low minimum wage state was more likely to have a job at all than was his counterpart in a high minimum wage state. Moreover, while jobs in high minimum wage states got raises as a result of the Federal minimum wage mandate, workers were less likely to be hired into those jobs.

As Clemens and Wither put it,

Over the late 2000s, the average effective minimum wage rose by 30% across the United States. We estimate that these minimum wage increases reduced the national employment-to-population ratio by 0.7 percentage point.

Clemens and Wither also had this:

We also present evidence of the minimum wage’s effects on low-skilled workers’ economic mobility. We find that binding minimum wage increases significantly reduced the likelihood that low-skilled workers rose to what we characterize as lower middle class earnings. This curtailment of transitions into lower middle class earnings began to emerge roughly one year following initial declines in low wage employment. Reductions in upward mobility thus appear to follow reductions in access to opportunities for accumulating work experience.

But Progressive Democrats know better. Facts are for the little people—you and me.