
Capital Gains Taxes and Federal Revenues

The Wall Street Journal offered a history lesson with empirical data relating taxes on investment to revenues collected by the government since 1977, a period when capital gains taxes were alternately raised and lowered by a capricious Congress.

This figure tells the story, which I’ll only summarize; you should read the whole lesson.
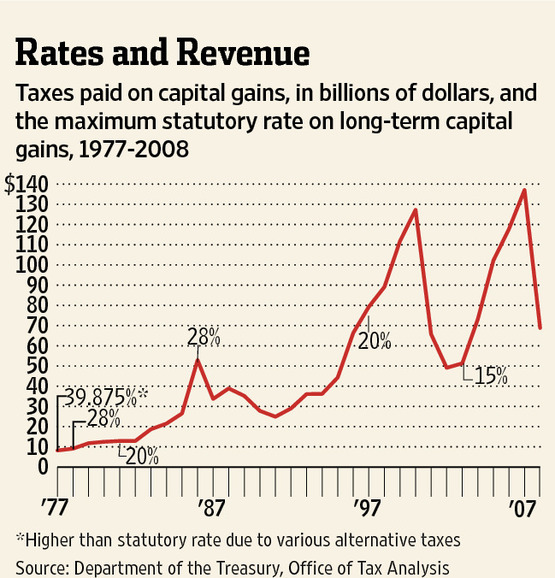
Essentially, raising tax rates—as has been noted for other Federal taxes—lowers tax revenues, and lowering the rates increases the collected revenues.

A couple of things in the figure are noteworthy, though.   The tax rate drop to 20% in 1981 did not lead to a drop in revenue—surprise—but 1982 was a year of a sharp recession, and collected revenue from that lowered rate still remained flat: no drop with the recession.  Collected revenue then ran up hard as we came out of the recession.  Additionally, the sharp drops after the sharp increases that resulted from the rate decreases in 1997 and 2003 came from the dot-com bubble burst that saw the NASDAQ, for instance, lose 60% of its value and from the Panic of 2008, whose hard recessionary effects we’re still in the middle of.

There’s another impact of higher capital gains tax rates, though, as the WSJ also points out.  High rates disinclines investors from selling their holdings as soon as they might.  This sequesters those investment monies in present investments, making them unavailable to other investments—younger, newer, more agile businesses with more current ideas, for instance—that might be better places, on a purely business basis, for investment dollars.  Moreover, the higher capital gains tax rates lower the returns on investments, leading other investors to demur from committing their funds in the first place to such investments.  The taxes distort the investment decisions.

But President Obama doesn’t care about healthy revenue collections for government; he doesn’t care about a healthy economy.  He cares about his definition of “fairness.”

GIBSON: So why raise [capital gains tax rates] at all, especially given the fact that 100 million people in this country own stock and would be affected?

OBAMA: Well, Charlie, what I’ve said is that I would look at raising the capital gains tax for purposes of fairness.

A Bill Under the Commerce Clause

Some view the Constitution’s Commerce Clause as granting to the Congress expansive powers of Federal control of intrastate activities, individual activities, and even the thoughts of private citizens.  A supine Supreme Court has supported this view.  Wickard v Filburn, for instance, agrees that Congress can regulate privately carried out agricultural activities, and NLRB v Jones & Laughlin extends that to manufacturing activity that occurs wholly within a state—an activity that prior to Jones & Laughlin was considered separate and distinct from any commerce-related process.  With these rulings in mind, a Federal District judge, Gladys Kessler, has even held that this Commerce Clause control extends into the private thoughts of individual citizens (Mead v Holder).

The line of reasoning for this startling evolution can be summarized in Chief Justice Charles Evans Hughes’ majority opinion in Jones & Laughlin: activities that are intrastate in character (which rather tautologically includes those individual activities) are regulable under the Commerce Clause when they bear a “close and substantial relation to interstate commerce.”

Agriculture is such an intrastate activity when the processes of field preparation, sewing, growing, and harvesting are considered separately, and separately from any subsequent process of bringing that harvest to market.  Likewise, manufacturing is such an intrastate activity when the processes of gathering equipment and locally procured supplies, the assembly of those supplies into finished product, and their in-plant inspection are considered separately, and separately from any subsequent process of bringing those finished products to market.  However, since Wickard and Jones & Laughlin hold such activities to bear a “close and substantial relation to interstate commerce,” it is reasonable to hold that any activity that impacts those processes of agriculture and manufacturing also bear a “close and substantial relation to interstate commerce.”  Such activities here plainly include union strikes and boycotts.

Accordingly, I propose a simple, one-page bill (no 2,000+ pages for me) that bans union strikes and boycotts, citing the Commerce Clause as the constitutional authority for such a ban.

It would be interesting to hear the Commerce Clause objections to such a bill.  What rationalizations might be offered?

Government Tax Increases and Government Spending Cuts

Stipulate, arguendo, that government spending is stimulative.  In order to pay for the stimulative spending, government must collect taxes or borrow.  Taxes taken away from the citizens, though, is money the citizens no longer can spend.  Raising taxes to pay for increased stimulative spending is even more money that those citizens now cannot spend.  This reduced private spending offsets the public spending funded by that taxation.

Increased taxes to support increased public spending reduces private spending even more than the amount of the tax increase, though.  The increment above the simple reduction in private spending comes from individuals and businesses now being especially careful to husband their monies: they increase their savings so as to improve their ability to handle unforeseen problems, such as a medical emergency, a roof repair, a capital plant problem, another increase in their tax bill beyond the one just suffered.  Thus, private spending is reduced further by increased saving, and a tax increase results in a net reduction in the sum of private and public spending.

This offset doesn’t change when government borrowing, rather than tax increases, is used to fund stimulative (government) spending.  Americans aren’t stupid.  We all recognize that today’s government borrowing is just tomorrow’s increased taxes and/or rising inflation, and so the above husbanding still occurs.

This is a relatively symmetric relationship.  A reduction in tax rates achieves two positive things (although after a minimum threshold, the second positive becomes a wasteful negative).  The first positive thing is that more money is left in the hands of private individuals and private businesses.  This additional money is either spent, which is directly stimulative, or it is saved against one of those unforeseen events, or for a planned large expenditure, future retirement, or future investment.

Thus, saving is stimulative tomorrow, and more than that, the saved money actually serves two stimulative roles.  One role is that this is the money private individuals and our businesses are going to spend tomorrow for one of the reasons just described.  The other role is through private or commercial lending/borrowing.  Those savings are assets that banks and other financial institutions can lend to our neighboring private individuals and to our businesses, so our neighbors and businesses have increased money for their current spending.

The second positive thing is that with these reduced tax rates, economic growth is encouraged, and that increased economic activity generates more revenue for the government beyond the direct reduction from those reduced rates.  However, since government has no need of money beyond funding the few things our government was created to effect, any amount beyond that level is wasteful and so provides room for reducing tax rates even further.

Finally, in the real world, where (Keynesian) stimulus spending has been shown to be wrong empirically (vis., FDR’s “stimulus” spending during the Great Depression, which prolonged the Depression; and Obama’s “stimulus” spending in the present deep recession, which is prolonging the recession), reduced government spending also is net stimulative.  Government spending crowds out private spending through at least two mechanisms.  Government demand artificially elevates prices compared to the level at which those prices would exist in the face of solely private demand, and private spending is reduced by lack of need to purchase: the government will buy and transfer the goods to the private individuals.  Reduced government spending reduces that crowding out, and private individuals and businesses return to the market place.

He Just Doesn’t Get It, Treasury Precinct

Eric Morath, of The Wall Street Journal, describes Secretary Treasury Timothy Geithner’s speech this week before the Economic Club of Chicago.  Geithner said,

The challenges facing the American economy today…are about the barriers to economic opportunity and economic security for many Americans and the political constraints that now stand in the way of better economic outcomes[.]

So far, so good.  But then, Geithner claims that the deficit- and debt-exploding “stimulus” spending this administration and its predecessor inflicted on our economy in 2008 and 2009 helped avoid a much deeper depression.  (As an aside, it’s interesting to note that, just as everyone else in this administration who’s made this claim has done, Geithner declined to offer any evidence whatsoever to support his claim.)  He also insists that government needs to do yet more to stimulate our economy.

Then he argued, in all seriousness, that cutting spending and taxes won’t stimulate the economy.  Here’s the Treasury Secretary insisting that leaving more of our money in our hands to spend—or save—according to our needs isn’t stimulative.

Additionally, here’s that same Treasury Secretary arguing the old, failed Keynesian thought that government spending, of its nature, is stimulative.  The thing with government spending, though, is that it crowds out private spending, it doesn’t add to it.  With the government buying, there’s less need for individuals or businesses to buy: government will, and give it to us.  Look at health care.  Look at food stamps (which I pick on due, among other things, to the impact of farm price supports and the government-mandated ethanol program on food prices).

And

There is no economic or financial case for using the fear of future deficits to cut as deeply into core functions of the government, to weaken the safety net or fundamentally alter Medicare benefits[.]

No, of course not.  He’ll just have more money printed up to cover those costs.  Never mind that all that inflowing printed currency is just inflation, either today or tomorrow, which will only erode the value of the money coming from that Federal spending—and the value of what money we still have after taxes.  The government can print money to keep up with its inflation.  We cannot.

No, Mr Geithner, the political constraints challenging our economy today consists entirely of too much Federal government interference in our economy.  The most important thing that government needs to do more of right now, to help our economy, to stimulate our economy, is to sit down and put its collective hands in its collective pockets.  Do more nothing

Recovery, and Recovery, and Recovery

…creeps in this petty pace.*  Here are some statistics, courtesy of Edward Lazear, writing for The Wall Street Journal.

  • In the three years [after the Great Depression of 1930-33], the economy rebounded with growth rates of 11%, 9%, and 13%, respectively.
  • The current recovery, beginning in 2009, has had growth rates of in 3% and 1.7% in 2010 and 2011, respectively.  The [2012] growth rate looks to be about 2%.
  • From post-WWII to the current recession (1947-2007), the US’ average annual growth rate was 3.4%.
  • Since the ’80s, we’ve had somewhat slower growth, but even here, the average growth rate was 3%.
  • During our current “recovery,” our economy has grown at 2.4%—below both that long-term trend, and the intermediate, nearby trend.
  • Today our economy is 12% smaller than it would have been had we matched our growth trend since 2007.
  • Today our economy is 4 per centage points further off trend line than it was 1Q09 when President Obama’s nearly trillion-dollar “stimulus” effort started.

Historically, the deeper the recession, the stronger the subsequent recovery.  The present “recovery” isn’t robust by any measure.  It’s not even catching up.

Whose policies have been in effect throughout this creeping, petty “recovery?”  Not those of Bush the Younger.

*With apologies to the Thane, Macbeth.